Roof damage after a severe storm is stressful enough. Complex insurance paperwork only adds pressure. You might feel overwhelmed seeing shingles in your yard or water spots on your ceiling.
Suppose a storm, fallen tree, or other covered event has damaged your roof in Ohio. Your homeowner’s insurance policy likely covers the cost of storm damage repair or replacement.
The claims process often feels confusing. A mistake early on can lead to a denial or a low settlement. Early documentation avoids most mistakes.
Already have a denial in hand? See our guide to what to do when your Ohio roof claim is denied. It covers the specific rule your insurer has to follow.
Wondering how long each step actually takes? See our real claim timeline, hour by hour, with the exact deadline behind every stage.
This guide is general information, not legal or insurance advice. Policies differ, so check yours with your insurer. Then contact the Ohio Department of Insurance or an attorney about your situation.
This guide breaks down exactly how to file a roof insurance claim in Ohio. We cover the main state claim rule. The guide also covers the practical steps.
Understanding Your Ohio Homeowner’s Insurance Policy
Know what you are looking at before you call your agent. Most standard homeowner’s insurance policies in Ohio cover roof damage caused by sudden, accidental events.
These are covered perils. They typically include hail, windstorms, fallen trees, fire, and vandalism.
Insurance generally does not cover damage resulting from age or lack of maintenance. An adjuster will deny your claim if they find age and neglect caused the failure.
Picture a 25-year-old neglected roof. Last week’s storm did not damage it. No public source reports an Ohio roof denial rate.
See the data review.
Key Policy Terms to Know
Deductible This is the amount you pay out of pocket before insurance pays a dime. Deductibles vary by policy. Some policies use a percentage deductible for wind or hail, such as 1% or 2% of the home’s insured value.
That can be much higher than a flat amount.
Actual Cash Value (ACV) An ACV policy pays the current, depreciated value of your roof. If your roof is 15 years old, the insurance company deducts value for those 15 years of usage. You will likely pay the gap between their check and the cost of a new roof.
Replacement Cost Value (RCV) This coverage pays the full cost to replace your roof with new materials of similar quality. Ask about RCV coverage, because it covers the gap that depreciation creates.
Check your declarations page immediately to see which coverage you have. The payout gap between ACV and RCV can be large.
| Feature | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
|---|---|---|
| Payout Basis | Depreciated value (Age is deducted) | Current market cost to replace |
| Out-of-Pocket Cost | High (Deductible + Depreciation) | Low (Deductible only) |
| Premium Cost | Typically lower monthly premiums | Higher monthly premiums |
| Best For | Older homes or budget-focused plans | Maximum financial protection |
Exclusions That Catch Homeowners Off Guard
Two policy details surprise many Ohio homeowners at claim time.
Cosmetic damage exclusions. Some Ohio insurers exclude cosmetic hail damage. If hail dented shingles but did not affect function, they may not pay.
Read your declarations page carefully.
Roof age limits. Some policies will not cover older roofs at all. Others switch to ACV coverage after a set age.
Your coverage may be lower than you expect.
Ohio’s Matching Rule
Ohio’s claim rule, Ohio Adm. Code 3901-1-54, speaks to matching. Under paragraph (I)(1)(b), an insurer replacing part of an item must replace enough of it.
The goal is a reasonably comparable appearance. The rule does not create a private right to sue.
Are your shingles discontinued or faded, so they cannot be matched? Ask your insurer how it applies this rule. Results depend on your policy and the facts, and a full roof is not guaranteed.

Step 1: Document the Damage Immediately
Start collecting evidence the moment you notice damage or after a storm passes through Lancaster. Thorough documentation is the single most important factor in disputing a low settlement later.
Take Detailed Photos and Video Capture the damage from the ground and, if safe, from a ladder. You want wide shots that show the house number and the roof in the same frame to prove location. Get close-up shots of missing shingles, dents in downspouts (a clear sign of hail), and any debris.
Note the Date and Time Record exactly when the damage occurred. Policies differ on how fast you must report a loss and how long you have to sue. Find both in your policy.
Waiting can let an insurer argue the damage is wear and tear.
Save Weather Reports Pull up weather data for your specific zip code on the date of the loss. Reports from the National Weather Service or local archives can link damage to specific wind speeds or hail sizes. This objective data makes it hard for an insurer to argue the storm wasn’t severe enough to cause damage.
Keep Damaged Materials Do not throw away fallen shingles or pieces of siding. These physical items serve as primary evidence. Stack them neatly in a corner of your yard or garage until the adjuster reviews them.
Step 2: Prevent Further Damage
Most policies expect you to protect the property from further damage. Take reasonable steps to stop it from getting worse. Skipping this can let an insurer deny later interior water damage.
Take these temporary measures if your roof is leaking:
- Place heavy-duty tarps over exposed roof decking.
- Use buckets to catch active drips in the attic or living spaces.
- Move furniture and electronics away from the affected area.
- Board up broken windows or openings.
Important Warning Do not make permanent repairs before the adjuster inspects the property. The adjuster needs to see the extent of the original damage. If you fix it completely, you destroy the evidence needed to approve your claim.
Keep all receipts for tarps and plywood. The Ohio Department of Insurance homeowners guide advises making temporary repairs and keeping receipts. Ask your insurer what it will reimburse.
Step 3: Contact Your Insurance Company
File your claim once you have your evidence gathered. Most carriers in Ohio have 24/7 claims hotlines and mobile apps. Examples: Nationwide, State Farm, and Erie.
Have this information ready when you call:
- Your policy number.
- Date and time of the loss.
- A brief, factual description of what happened (e.g., “Wind storm blew off shingles”).
- Confirmation that you have taken steps to prevent further damage.
The insurer will assign a claim number and an adjuster. Under Ohio Adm. Code 3901-1-54(F)(2), the insurer must acknowledge your claim within 15 days.
Under (G)(1), it must accept or deny within 21 days of proof of loss. Otherwise it must tell you why it needs more time. Undisputed amounts are due within 10 days of acceptance.

Step 4: Get a Professional Roof Inspection
Schedule an inspection with a local, licensed roofing contractor before the insurance adjuster arrives. A professional roofer works for you, while the adjuster works for the insurance company. You need an expert in your corner who knows what to look for.
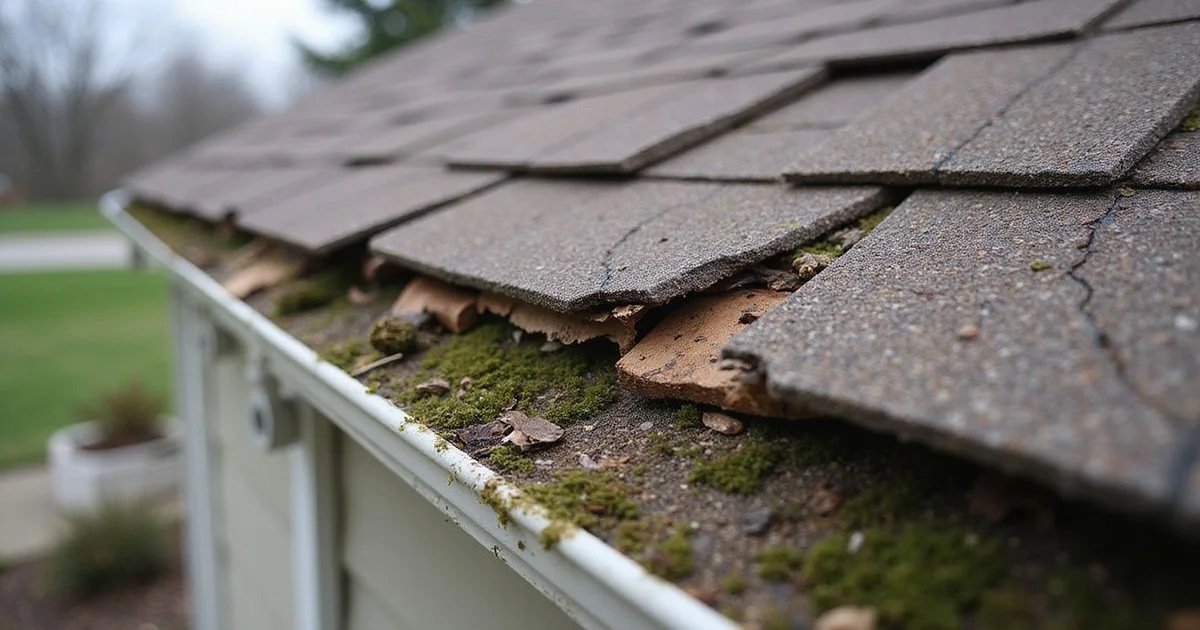
Some damage is easy to miss. Subtle signs like “bruised” shingles are easily overlooked by an untrained eye.
Hail has compromised the matting but not broken the surface. These shingles will lead to leaks later.
A proper contractor inspection report should include:
- Diagram of the Roof: Measurements of the square footage, pitch, and layers.
- Photos with Annotations: Circle the damage directly on the images.
- Scope of Work: A detailed list of everything that needs to be removed and replaced.
- Local Code Requirements: Identification of Ohio Building Code upgrades required during replacement.
Ask your contractor for one. Have the file ready before the adjuster arrives.
Step 5: Meet with the Insurance Adjuster
The on-site inspection is the turning point of your claim. The adjuster’s report forms the basis of the initial settlement offer. You or your contractor must be there to influence this process.
Be Present Make sure you are home. You have the right to walk the property with the adjuster and point out the specific issues you documented in Step 1.
Have Your Contractor Present This is the most effective way to ensure a fair assessment. When a contractor is present, they can discuss the damage in real-time using industry terms. It is much harder for an adjuster to ignore damage when a professional is pointing directly at it.
Discuss Scope, Not Price Focus on agreeing on what is damaged (the scope of loss). Do not argue about the price of a shingle bundle yet. If you agree that the East and North slopes need replacement, the pricing can be fixed later using standard industry software like Xactimate.
Step 6: Review the Settlement Offer
You will receive a settlement offer or a “Statement of Loss” after the inspection. Review this document line-by-line against the estimate your contractor provided.
Look for these common discrepancies:
- Missing Components: Did they include starter shingles, ridge caps, and drip edges?
- Wrong Waste Factor: Did they allow enough extra material for cutting and fitting (complex roofs need more)?
- O&P (Overhead and Profit): When a job needs several trades, such as roofing, gutters, and interior paint, contractors often request overhead and profit. Insurers may omit it unless asked. Ask your insurer how it handles it.
Code Upgrades are Critical Ohio building codes change over time. If your home was built in 1990, it likely lacks the ice and water shield or intake ventilation required today. If you have “Ordinance or Law” coverage, your policy must pay for these required upgrades.

Step 7: Supplement the Claim
Do not panic if the first check is low. This is just the starting offer.
The insurance process allows supplements. These are official requests for additional funds to cover missed items or price differences.
How the Supplement Process Works Your contractor will submit a document proving why the additional funds are needed. This might include photos of code requirements or invoices showing that local material prices have risen.
Request a Re-inspection You can demand a second look if the first adjuster denied obvious damage. Many underpayments come from missed items, which a second look can catch.
Know Your Rights The Ohio Department of Insurance takes consumer complaints about insurers. You can file one if you think your insurer is delaying or underpaying. The Department cannot give legal advice.
How Adjusters Assess Roof Damage in Ohio
Adjusters follow a set protocol. The depth varies by adjuster and claim volume. After a major storm, adjusters can be very busy.
Inspections may be short.
What they look for on hail claims. They check for circular bruise marks where granules have come loose. They also check soft metal like gutters, flashing, pipe boots, and ridge cap for dents.
Some insurers set a minimum hit count per test square for full replacement. Ask yours.
What gets missed. Damage under the ridge cap is easy to miss because it takes removal to see. So is damage to step flashing and chimney flashing.
Underlayment punctures and low-visibility roof sections also slip by. Having your contractor on site lowers the odds of missed items.
Why Xactimate can run low. Xactimate is the software adjusters use to price repairs. It pulls from a regional price database that updates only periodically.
Its figures can run below actual contractor quotes. A gap does not mean your contractor is overcharging. The software may lag the market.
Documentation can help you dispute the number.
What to Do If the Settlement Is Too Low
A low offer is not the final word. You have three options, in rising order of effort.
Option 1: Request a re-inspection. Ask for a second adjuster visit with your contractor present. Hand over the written contractor estimate for comparison.
Many underpayments come from missed items and are fixed at this stage.
Option 2: Hire a public adjuster. A public adjuster works for you, not the insurer. They inspect the damage and negotiate on your behalf.
Ohio licenses public adjusters. Fees are usually a percentage of the settlement.
See the Ohio Department of Insurance public adjuster page. Ask for the fee in writing and compare it to the likely gain.
Option 3: Invoke the appraisal clause. Many homeowner policies include an appraisal clause. The Ohio Department of Insurance homeowners guide describes it.
Each side names an appraiser. The two pick a neutral third party if they disagree.
Read your policy for how binding the result is. This takes longer but can avoid a lawsuit.
These options apply when the insurer agrees the damage is covered but disputes the payout. If they denied the claim outright, the appraisal clause will not help.
A warning on assignment of benefits. Do not sign an assignment of benefits (AOB) before you understand it. An AOB hands your claim rights to a contractor.
It has legitimate uses. Some contractors misuse it to inflate claims or take fees that belong to you.
Questions to Ask Your Carrier
Every insurer runs claims a little differently. Ask yours these questions up front.
- What hail or wind criteria do you use to approve full replacement?
- Does my policy pay replacement cost or actual cash value for the roof?
- Do I have Ordinance or Law coverage for code upgrades?
- How do you handle matching when shingles are discontinued?
- When will I get a written decision?
Common Mistakes That Can Hurt Your Claim
Avoid these specific errors to keep your claim valid:
- Waiving Your Deductible: Contractors who offer to waive or rebate your deductible are widely treated as committing insurance fraud. Ask your insurer and the Ohio Department of Insurance before agreeing.
- Signing a “Contingency” Too Early: Read the fine print. Ensure you aren’t locking yourself into a contract before you know if the claim is approved.
- Accepting ACV as Final: If you have RCV coverage, the first check is just the ACV payment. You get the rest (recoverable depreciation) after the work is done and invoiced.
- Missing the Filing Window: Report the loss soon and check your policy deadlines. Evidence fades fast.
- Not Knowing Your Deductible Type: Wind and hail deductibles may be a percentage of insured value. On a $250,000 home with a 2% deductible, that is $5,000 out of pocket.
- Accepting the First Estimate Unreviewed: The first Xactimate estimate is often incomplete. Compare it line by line with your contractor's estimate.
- Skipping Temporary Repair Records: Keep receipts and photos for emergency tarping. Without them, these costs are hard to recover.
One more mistake is skipping the tax side. Owners can ask the county auditor for a value deduction on Form DTE 26.
Sources
- Ohio Adm. Code 3901-1-54, unfair property/casualty claims settlement practices
- Ohio Department of Insurance, consumer complaint information
- Ohio Department of Insurance, homeowners insurance guide
- Ohio Department of Insurance, using a public adjuster
Frequently Asked Questions
How do I file a roof insurance claim in Ohio?
Document all damage immediately with photos and video. Take temporary protective measures if safe, such as tarps or boards. File a claim with your insurer.
Get a professional roof inspection before the adjuster visit. Use the detailed inspection report when reviewing and negotiating the settlement offer.
What does Ohio homeowners insurance cover for roof damage?
Ohio policies typically cover sudden storm damage such as wind, hail, lightning, and falling trees. Gradual deterioration, maintenance neglect, and pre-existing conditions are generally excluded. Policy terms vary.
Review your declaration page carefully.
What is Ohio's matching statute for roofing?
Ohio Adm. Code 3901-1-54(I)(1)(b) covers matching. It applies when an insurer replaces part of an item.
The insurer must replace enough to give a reasonably comparable appearance. Whether that means a full roof depends on your policy and the facts.
How long do I have to file a roof damage claim in Ohio?
Your policy sets its own notice and suit deadlines. Read it or ask your insurer. Report damage promptly.
Late claims are harder to document and easier to dispute.
Should I hire a public adjuster for my Ohio roof claim?
A public adjuster can help with large or disputed claims. They usually charge a percentage of the settlement. Get the rate in writing first.
A roofing contractor can also document damage to support your claim.
What can I do if my Ohio roof insurance settlement is too low?
There are three options in rising order of effort. Request a re-inspection with your contractor present. Hire a public adjuster.
They usually charge a percentage of the settlement. Or use the appraisal clause in your policy, if it has one. Compare the first offer to an actual contractor estimate before accepting it.
What is Xactimate and how does it affect my roof claim?
Xactimate is the software adjusters use to calculate repair costs. It pulls from a regional pricing database that updates periodically. Its pricing can lag current contractor quotes.
A gap between the insurer's estimate and your contractor's bid can happen. Documentation can help you dispute it.
Getting Help with Your Insurance Claim
Filing a roof insurance claim requires attention to detail and patience. Fairfield Peak Roofing connects Lancaster and Fairfield County homeowners with independent local contractors. Many offer storm damage inspections and help with supplement paperwork.
See what an insurance claim roofing contractor does and what only your insurer decides.
Call 877-367-1885 to ask about availability at your address. A contractor can assess your damage and give you data for your decision.
Need Help with Your Roof?
Get an inspection and estimate from Lancaster's most trusted roofing team.